Order Rounding and Step Size: Why Automated Trades Get Rejected
You automate a strategy, the signal fires, and the order comes back rejected. No fill, no position, just an error code to decode after the moment has passed. Mo...
Read more
The bid-ask spread is the quiet execution cost every automated market order pays. Here is what it is, why it exists, and how it shapes your fills.
Your strategy fires a buy signal, the order goes in, and it fills a few ticks above the price you saw on the chart. Nothing broke. That gap is the bid-ask spread, and for anyone running automated orders it is a quiet, recurring execution cost that shows up on every market fill. This guide explains what the bid-ask spread is, why it exists, and exactly how it affects the fills your automation receives — so you can set up your trading with clear eyes instead of blaming the relay when a fill lands where it should.
Every crypto market has two live prices, not one. The bid is the highest price a buyer is currently willing to pay. The ask (or offer) is the lowest price a seller is currently willing to accept. The bid is always lower than the ask, and the difference between them is the spread.
When you look at a "price" on a chart, you are usually seeing the last traded price or the midpoint. But you cannot trade at the midpoint with a market order. If you buy, you pay the ask. If you sell, you receive the bid. The spread is the toll you cross to get an immediate fill.
On a liquid pair like BTC/USDT, that toll can be a single tick — a tiny fraction of the price. On a thin, low-volume altcoin, the spread can be wide enough to notice immediately. Either way, it is real, and automation pays it just as manual trading does.
The spread is not a fee an exchange invents. It emerges from the order book — the live list of resting buy and sell orders. Market makers and other participants post limit orders on both sides and earn the spread as compensation for providing liquidity and taking on inventory risk.
Two forces set how wide it gets:
Understanding both forces matters because your automation does not choose when signals arrive. It executes when the strategy says to, and market conditions at that moment decide the spread you cross.
Here is the mechanism that trips people up. A market order takes whatever price is available right now, which means it crosses the spread on entry and crosses it again on exit. A round trip pays the spread twice before the trade has done anything.
Because most signal-driven automation uses market orders for reliability — they fill immediately and never get left hanging — every automated fill absorbs the spread by design. That is usually the correct trade-off: a filled order at a slightly worse price beats a limit order that never executes because price ran away. But it means the spread is baked into your execution, and you should expect fills at the ask (buys) or the bid (sells), not at the mid.
The spread also compounds with slippage. Slippage is the extra movement when your order is large enough to eat through several price levels. Spread is the cost of crossing the top level; slippage is the cost of crossing the ones beneath it. On a liquid pair with a small order, you mostly pay the spread. On a thin pair or with a large order, you pay both.
The practical picture:
None of this is a malfunction. It is the market telling you what immediacy costs at that instant.
A one-tick spread feels like nothing on a single trade. The reason it deserves attention in automation is frequency. A manual trader might take a handful of trades a week. A strategy running around the clock across several pairs can generate many fills a day, and each one crosses the spread on both sides.
Multiply a small per-trade cost by a high trade count and it becomes a meaningful drag on execution quality — not because anything is broken, but because you are paying for immediacy repeatedly. High-frequency strategies on thin pairs feel this most. This is also why the same signal logic can perform very differently on a liquid pair versus an illiquid one: the strategy is identical, but the spread cost is not. If you want to see the raw cost, compare the fee side too, since crossing the spread means you are usually the taker and pay taker fees on top.
You cannot eliminate the spread, but you can manage how much of it you pay:
SignalToExchange is a non-custodial webhook relay — it receives your signal and submits the order to your exchange with trade-only API keys, so your funds never leave the exchange and no one can withdraw them. It does not set the spread and does not choose your order type for you; the exchange's live order book determines your fill, and your strategy decides whether to send a market or limit order. What the relay does is make sure the order you intended actually reaches the exchange quickly and once, so the only cost you are exposed to is the market's, not a missed or duplicated order. You control the logic. We handle the relay.
No. The spread is a normal cost of immediate execution, not a sign of a problem. Every market participant who wants an instant fill pays it. It is worth understanding and managing, but crossing the spread is simply what a market order does.
Only by using resting limit or post-only orders that provide liquidity instead of taking it — and those risk not filling if price moves away. Market orders, which most signal automation relies on for reliability, always cross the spread. The practical goal is to minimize the cost, not eliminate it.
Your chart likely displayed the last traded price or the midpoint. A market buy fills at the ask and a market sell fills at the bid, so a fill slightly away from the charted price is the spread doing exactly what it should. Wider gaps usually mean the pair was thin or volatile at that moment.
No. Spreads vary by exchange because each has its own order book and liquidity. The same token can be tight on a high-volume venue and wide on a smaller one, which is why pair and exchange choice affects your automated execution costs.
Understanding the bid-ask spread turns a confusing fill into an expected one. If you are ready to run your signals through infrastructure that keeps your funds on your own exchange and submits every order reliably and once, request access or start your free trial and connect trade-only keys to get going.
Automated trading involves risk. SignalToExchange is execution infrastructure and does not provide financial advice, trading signals, or guarantees of any kind.
You automate a strategy, the signal fires, and the order comes back rejected. No fill, no position, just an error code to decode after the moment has passed. Mo...
Your TradingView alert fires, the webhook reaches your exchange, and then nothing happens. The order comes back rejected. One of the most common reasons is the...
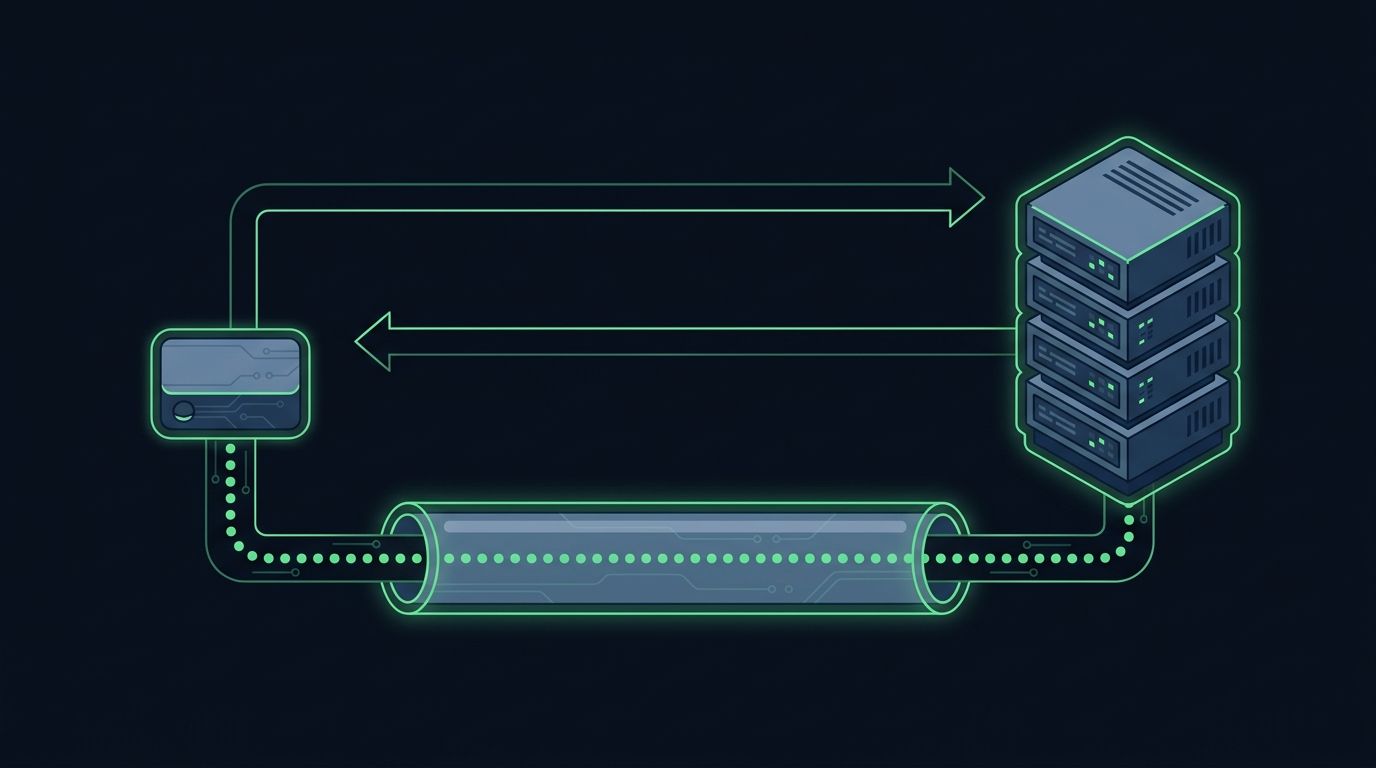
If you are wiring a strategy up to an exchange, one of the first technical forks you hit is WebSocket vs REST APIs on a crypto exchange. Both let your code talk...
Non-custodial execution. Trade-only API keys. Independent infrastructure built for reliability.
Request Early AccessTrade-only API key enforcement. No withdrawal permissions. No custody.